My billionaire future father-in-law sneered, “Street trash,” right at dinner in front of twenty guests. I slowly stood up and whispered, “Enjoy your meal, Silas. I just cut the only lifeline keeping your company afloat. I am now the owner of your empire.” His face went rigid.
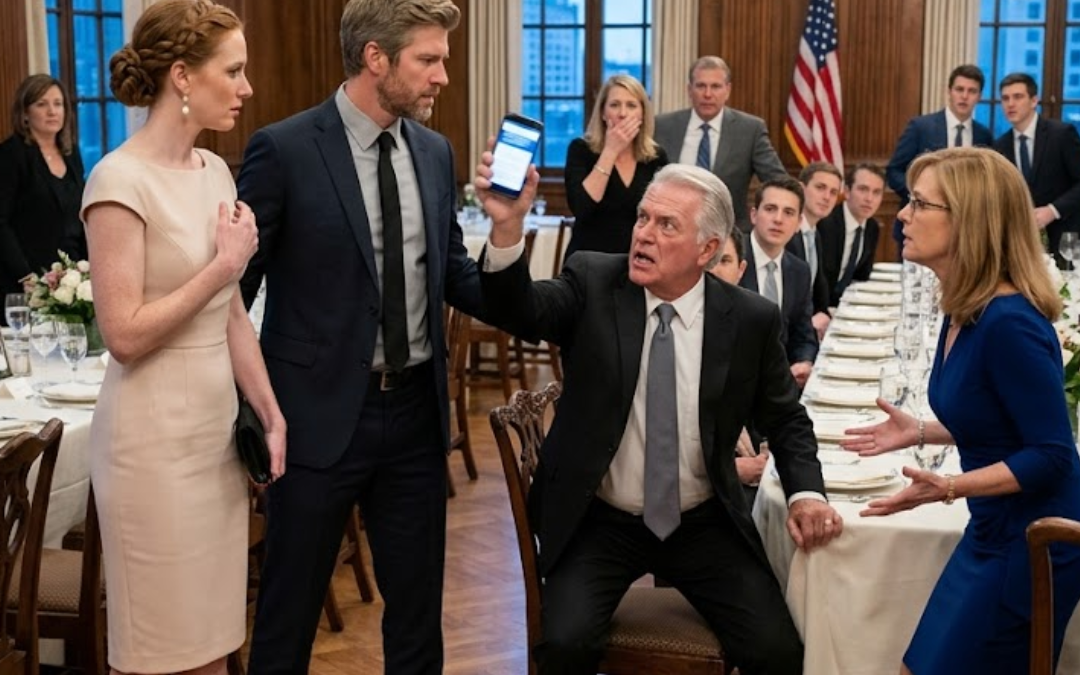
At Silas Vaughn’s dinner, twenty guests watched him sneer.
“Street garbage doesn’t become respectable because my son puts it in a better dress.”
Evan stood immediately.
“That’s enough.”
I opened my phone beneath the table, sent one message, and rose.
“Enjoy the meal, Silas. I just terminated your company’s only lifeline.”
He laughed.
Seconds later, his chief financial officer’s phone buzzed.
“The buyer withdrew.”
Silas froze when a director added, “The woman you just insulted controls the buyer.”
But that wasn’t the twist.
Three weeks later, the board would ask me to come back—and the company would be worth less.
Before I explain how, hit like. Tell me where you’re listening from, and share if someone ever judged your past before learning what you controlled.
My name is Mara Keane. I was 38, lived in Chicago, and ran Harborstone Capital Partners, an investment firm focused on transportation, logistics, and industrial turnarounds.
Silas knew none of that when he decided my childhood explained my worth.
I grew up in Tulsa, Oklahoma. My father left when I was eight. My mother cleaned motel rooms, worked night shifts at a nursing home, and took whatever job kept the rent paid.
When I was thirteen, we were evicted.
For almost a year, home meant an extended-stay motel, a friend’s spare room, or transitional housing. We used food assistance. I ate free lunch at school.
I never hid that history. I simply stopped believing that surviving poverty required me to apologize to anyone for having once been poor.
At seventeen, I took a night job dispatching trucks for a small carrier.
That job changed everything.
I watched drivers lose hours waiting at loading docks. I saw trucks run empty because dispatchers worked from paper schedules and fax machines. Customers called asking where their freight was, and nobody could answer quickly.
I became obsessed with fixing systems that wasted time and money.
I started at community college, transferred to a university, and graduated with debt, scholarships, and more work experience than sleep.
At twenty-seven, I founded Relay Grid Technologies. We built software for routing, fleet scheduling, shipment visibility, and warehouse appointments.
Eight years later, Relay Grid had more than four hundred employees and hundreds of enterprise customers. I sold controlling interest in a transaction valued at around $760 million.
That did not make me a billionaire.
Taxes, employee equity, early investors, and dilution took their shares. What the sale gave me was enough capital and credibility to build Harborstone.
By the time I met Evan, Harborstone managed roughly $3.6 billion for pension funds, insurers, endowments, family offices, and our partners.
We bought companies with good operations and bad capital structures.
I understood debt because I had grown up around scarcity. I understood leverage because I had spent my childhood without any.
Silas heard motel, food assistance, and community college and saw something beneath him.
What he did not understand was that the company carrying his name had already reached the kind of trouble my entire career had been built to recognize.
I met Evan Vaughn almost three years before that dinner.
He was forty-one, an orthopedic surgeon in Chicago, and one of the few people I had dated who seemed uninterested in what my balance sheet looked like.
Evan knew I had built Relay Grid and that I ran Harborstone. He did not know Harborstone was evaluating his father’s company.
That was not secrecy inside our relationship. It was a legal boundary.
The transaction was covered by nondisclosure agreements, and Evan had no role at Vaughn Freight Systems. He was not a director, trustee, executive, or adviser.
He had chosen medicine because he wanted a career that did not depend on his father’s approval.
Silas never forgave him for it.
Silas Vaughn was sixty-nine and had built Vaughn Freight Systems from two trucks into a major transportation company.
He deserved credit for that.
He had driven overnight routes, repaired equipment himself, negotiated contracts at loading docks, and survived downturns that destroyed larger competitors.
That history was why nobody around him challenged the belief that eventually grew from it.
Silas no longer thought he ran Vaughn Freight.
He thought Vaughn Freight was him.
Financial magazines estimated his net worth at between $1.3 billion and $1.5 billion, but most of that wealth existed in company shares, industrial property, and investments.
Silas was rich enough to make any room bend around him.
He was not liquid enough to solve every corporate problem with a check.
His wife, Maryanne, had been beside him for forty-three years. She was warmer than Silas, but she had spent decades managing his temper instead of confronting it.
Whenever he made a cruel remark, she would say, “Silas, enough,” in the same tone someone might use when a guest had poured too much wine.
Evan was different.
The first time Silas asked whether I understood family wealth, Evan answered, “She built more of her own than I ever will.”
That did not impress Silas.
It irritated him.
He saw my community-college start, motel childhood, and mother’s housekeeping jobs as stains that success could cover but never erase.
Once, after I left the room, he told Evan, “She polished herself well.”
Evan told me immediately.
I asked why his father cared so much about where I had started.
“Because if where you start doesn’t determine where you belong,” Evan said, “then half of what Dad believes about status falls apart.”
I thought that was a family problem.
I did not yet realize Silas was bringing the same belief into negotiations over a company he no longer had enough votes or money to control alone.
Vaughn Freight Systems looked powerful from the outside.
It had 6,800 employees, more than three thousand tractors, forty-nine terminals, and eleven warehouse campuses. Annual revenue was $2.7 billion.
The problem was not the business.
It was the debt Silas had layered on top of it.
Three years earlier, he had bought a cold-chain competitor at the top of the market and financed too much of the purchase with borrowed money. He believed scale would solve the rest.
Instead, integration dragged on. Maintenance costs climbed. Insurance claims rose. Interest rates moved against him. Two major customers failed to renew.
Operating earnings fell from about $290 million to $148 million.
Vaughn Freight still moved freight every day, but it carried roughly $840 million in funded debt, including a $390 million term loan due in four months.
The lenders would not refinance under the existing structure. They wanted fresh equity, asset sales, or a change of control.
Silas hated all three options.
The board did not have that luxury.
The independent directors hired an investment bank and formed a special transaction committee to evaluate buyers.
That was how Harborstone entered the process.
No one at Vaughn Freight learned about the opportunity through Evan. The banker contacted us directly.
The moment I realized the target belonged to my fiancé’s family, I disclosed the relationship to our investment committee, the seller’s counsel, and the special committee.
Evan was placed behind an information barrier. He saw no financial models, diligence reports, valuation work, or bid documents.
Harborstone submitted its offer through an acquisition vehicle called HCP Lantern Acquisition LLC.
Inside the sale process, the transaction became Project Lantern.
Silas knew a sophisticated financial buyer was negotiating with the committee, but the committee limited bidder-identifying details because he had already tried contacting potential buyers outside the process and bargaining for his own post-closing role.
The committee, banker, chief financial officer, and lawyers knew Harborstone was behind Lantern.
Silas did not.
Our initial offer valued the business at approximately $1.26 billion.
We proposed refinancing the debt, adding $150 million in operating capital, keeping most terminals open, and retaining most employees.
The competing offers were either lower, slower, or built around deeper cuts.
There was only one major obstacle.
Silas wanted to sell the company without surrendering control.
He demanded an executive-chairman title, hiring vetoes, strategic approval rights, and access to the corporate aircraft.
Harborstone refused.
Silas told the board the buyer would eventually bend.
At dinner, he was about to prove exactly why we would not.
The dinner took place at Silas and Maryanne’s estate in Mission Hills.
There were twenty people at the table: family members, two independent directors, senior executives, a banking couple, and several longtime friends who had known the Vaughns for decades.
I expected tension.
I did not expect Silas to turn my childhood into entertainment.
Before dinner, one of the directors asked whether the rumors about Vaughn Freight seeking outside capital were true.
Silas smiled over his wine.
“Whoever writes the check can put their name on the paper. I’ll still be running Vaughn Freight.”
I said nothing.
But that sentence confirmed exactly what Harborstone’s investment committee had been worried about.
Silas did not view a buyer as an owner. He viewed one as a source of money.
He wanted our capital, our lenders, and our credibility while keeping every decision that had helped push the company toward its deadline under his control.
Later, a guest asked where I had gone to college.
“I started at community college,” I said.
Silas leaned back.
“Community college leaves out the interesting part.”
Evan’s expression changed.
“Dad.”
Silas ignored him.
He mentioned the motel, the food assistance, and my mother cleaning rooms.
Then he looked directly at me.
“Street garbage doesn’t become respectable because my son puts it in a better dress.”
The table went silent.
Evan stood immediately.
“That’s enough. You don’t speak to her that way.”
I touched his arm.
“Give me one second.”
Silas smirked as though he had proved something.
I opened my phone beneath the table and sent a secure message to Harborstone’s transaction counsel.
Withdraw Project Lantern’s indication of interest. Effective immediately. Preserve the file.
Then I stood.
“Enjoy the meal, Silas. I just terminated your company’s only lifeline.”
He laughed.
“You have no idea what keeps my company alive.”
“That may be the first thing tonight you’re wrong about.”
Evan and I walked toward the foyer.
Behind us, Daniel Cho’s phone buzzed.
The chief financial officer read the message twice.
“Project Lantern withdrew.”
Silas turned sharply.
“Call them back.”
Daniel did not move.
Silas looked toward Margaret Sloan, the lead independent director.
“What happened?”
Margaret stared at him.
“The woman you just called street garbage controls the buyer.”
Silas stopped breathing for half a second.
“She works for them?”
“She controls them.”
His face hardened.
“Then reinstate the offer.”
The investment banker finally spoke.
“You don’t get to reinstate someone else’s bid.”
For the first time that evening, nobody looked at me like the person who had been humiliated.
They looked at Silas like the man who had just insulted his way out of the only transaction likely to close before the debt came due.
Outside, Evan asked, “Was Harborstone buying Vaughn Freight?”
“We were considering it.”
“Why didn’t you tell me?”
“Because it wasn’t mine to tell you.”
He stared ahead for a moment.
Then he said, “Do what you would do if you had never met me.”
I thought the deal was over.
Three weeks later, Margaret called.
The board wanted Harborstone back.
But by then, Vaughn Freight was worth less than it had been at dinner.
The morning after dinner, Margaret did not call me.
That mattered.
The special committee did what a responsible board was supposed to do before crawling back to the buyer Silas had insulted.
They reopened discussions with the other bidders, asked the lenders for more time, and reviewed whether Vaughn Freight could survive through asset sales instead of a change of control.
They also asked Silas how much personal capital he was willing to contribute.
His answer was none.
He called it irresponsible to throw private money at corporate debt.
Margaret later told me that was the moment several directors stopped believing his speeches about protecting the company.
Silas wanted authority treated as personal property and risk treated as everyone else’s problem.
The strategic bidder remained interested at roughly $1.18 billion, but antitrust review would take longer. Its financing was not fully committed, and its plan included closing overlapping terminals.
The distressed fund could move faster, but its offer was around $1.1 billion and came with deeper layoffs and warehouse sales.
Neither solved the lender deadline cleanly.
Meanwhile, deeper diligence produced worse news.
Vaughn Freight had delayed $52 million in fleet maintenance to preserve cash. Updated actuarial work showed its self-insured claims reserve was short by approximately $27 million.
Two contracts representing almost ten percent of annual revenue were approaching competitive rebids.
None of it was fraud.
It simply meant our original valuation had assumed a healthier company than the records now supported.
Three weeks after dinner, Margaret called.
“Would Harborstone reconsider?”
“I’ll take it back to committee.”
I did not say yes.
I did not say Silas had cost himself $80 million.
Our team rebuilt the model from the new information.
The revised enterprise value was $1.18 billion.
Every reduction was documented: the maintenance backlog, claims exposure, customer-renewal risk, and one additional factor that now had evidence behind it.
Founder-transition risk.
Our new terms were stricter.
Silas would receive no executive-chairman role, no hiring veto, no strategic-approval rights, no corporate-aircraft access, and no office with operational authority.
The company would receive a $175 million liquidity and modernization program, employee-retention commitments, an independent compliance committee, and a formal search for a new chief executive officer.
When Margaret presented the offer, Silas exploded.
“She’s using this company to settle a personal score, Margaret.”
“Then explain the maintenance backlog without mentioning dinner.”
He could not.
The board voted six to one to recommend the transaction.
Silas was the only no.
Then came the shareholder vote.
Silas owned twenty-nine percent. The family trust held eighteen percent, but an independent corporate trustee controlled those votes.
Institutional and legacy investors held most of the rest.
Evan did not call the trustee.
I did not contact the trustee.
Harborstone did not ask either of us to.
The shareholders received the fairness materials, financing commitments, and alternative-bid analysis.
Approximately sixty-eight percent voted yes.
Silas stared across the boardroom.
“This is my company.”
Margaret closed the voting report.
“It is a corporation, Silas—not an inheritance with employees.”
The acquisition would be financed with roughly $480 million in fund and co-investor equity, plus approximately $700 million in committed senior financing.
There was no personal billion-dollar check from me.
There was no overnight takeover.
The lawyers still had antitrust filings, lender payoffs, insurance transfers, and closing conditions to finish.
The closing date was set for nine weeks after dinner.
Silas signed nothing willingly, but he still believed that when the papers closed, the Vaughn name on every truck would force me to give him some version of control back.
That was the final assumption I intended to correct.
He was wrong about that, too.
Nine weeks after the dinner, the acquisition closed.
Harborstone’s vehicle took eighty-two percent voting control of Vaughn Freight Systems.
Silas received the same consideration for his shares that every other holder in his class received.
He was still wealthy.
What he lost was control.
That morning, the Vaughn name remained on the headquarters, the trucks, and every terminal sign.
Silas arrived for the first board meeting as though that meant nothing had changed.
He walked into the room, looked at me, and said, “You may own paper. This is still my company.”
“No,” I said. “It stopped being your company when the transaction closed this morning.”
He gave a bitter laugh.
“You think buying votes makes this your empire?”
“I don’t think it does.”
I placed the closing binder on the table.
“I own your empire.”
The room went silent—not because the line was dramatic, but because every signature beneath it made the statement true.
The new board had already been seated.
I chaired the meeting.
Daniel Cho remained as interim chief executive officer while an independent search began.
Evan was not on the board. He was not getting a job. He was still a surgeon.
This was not a family coup.
It was a change of control.
I introduced the motion to terminate Silas Vaughn’s employment as chief executive officer and remove all executive authority, effective immediately.
The board voted yes.
Silas stared at me.
“You cannot fire me from the company I built.”
“Building something does not give you permanent ownership of everyone inside it.”
He received the severance required by his contract, time to collect his personal property, and a formal transition process.
No security guards dragged him out.
No one applauded.
I did not need a spectacle.
The company itself was the result.
We kept the Vaughn Freight name because customers trusted it and employees had spent careers building it.
The $175 million modernization program began that month.
Fleet maintenance resumed. Dispatch systems were scheduled for replacement. Most terminals remained open. Most of the 6,800 employees kept their jobs.
Silas had assumed revenge meant making him poor.
I left him rich.
What I took was the one thing he had mistaken for a birthright:
The power to decide for everyone else.
His name stayed on the trucks.
His orders did not.
One year later, even Maryanne would admit that the dinner had not cost Silas his company.
His arrogance had.
One year later, Vaughn Freight was moving freight under the same name.
The maintenance backlog had fallen sharply. Dispatch technology had been replaced. Safety metrics had improved, and two major customer contracts had been renewed.
We consolidated two small sites, but most of the 6,800 employees stayed.
Silas remained wealthy.
He no longer had an office, a board seat, or the right to treat the company like an extension of himself.
Maryanne stopped calling the acquisition revenge.
Evan never joined Vaughn Freight. He stayed in medicine, and we postponed our wedding until the transaction ended.
Eight months after closing, we married.
Silas did not apologize.
Instead, he sent one letter.
You were waiting for a chance to take what I built.
I answered once.
I was willing to pay more before I met the version of you who believed ownership meant no one could tell you no.
He never replied.
Silas believed wealth decided who belonged at the table.
He learned too late that the woman he seated beneath him controlled the capital keeping his chair in place.
His name was still on the trucks.
The decisions were not.
Would you have walked away after that dinner, or gone back and bought the company?
Comment below and subscribe for more clean revenge stories.